A and D Adjusters reads your policy, documents the damage and presents your claim to the carrier on your behalf. Wind, hail, water and fire. Homes and commercial buildings across Chicagoland.
A and D Adjusters
Illinois Public Adjuster License number: on file once issued
Serving Cook, DuPage, Lake, Will, Kane and McHenry counties
A public adjuster is licensed by the Illinois Department of Insurance to represent the policyholder in a property claim. The adjuster your insurance company sends is paid by the insurance company. A public adjuster is hired by you, works for you, and is paid only out of what the policy pays. We do not work for any insurer, and we are not part of any state agency.
We start by reading the whole policy, including the endorsements and the deductible schedule that decide what a wind or hail claim is actually worth. Then we go to the property, photograph and measure the damage, and write a line-item scope of the loss. We present that scope to your carrier and handle the back and forth with their adjuster, so you are not the one on the phone explaining your own roof.
If the claim already looks fairly paid, we tell you that and you owe us nothing. The first look is free. If we take the claim, our fee is a percentage of the settlement and it is written into the contract before any work begins.
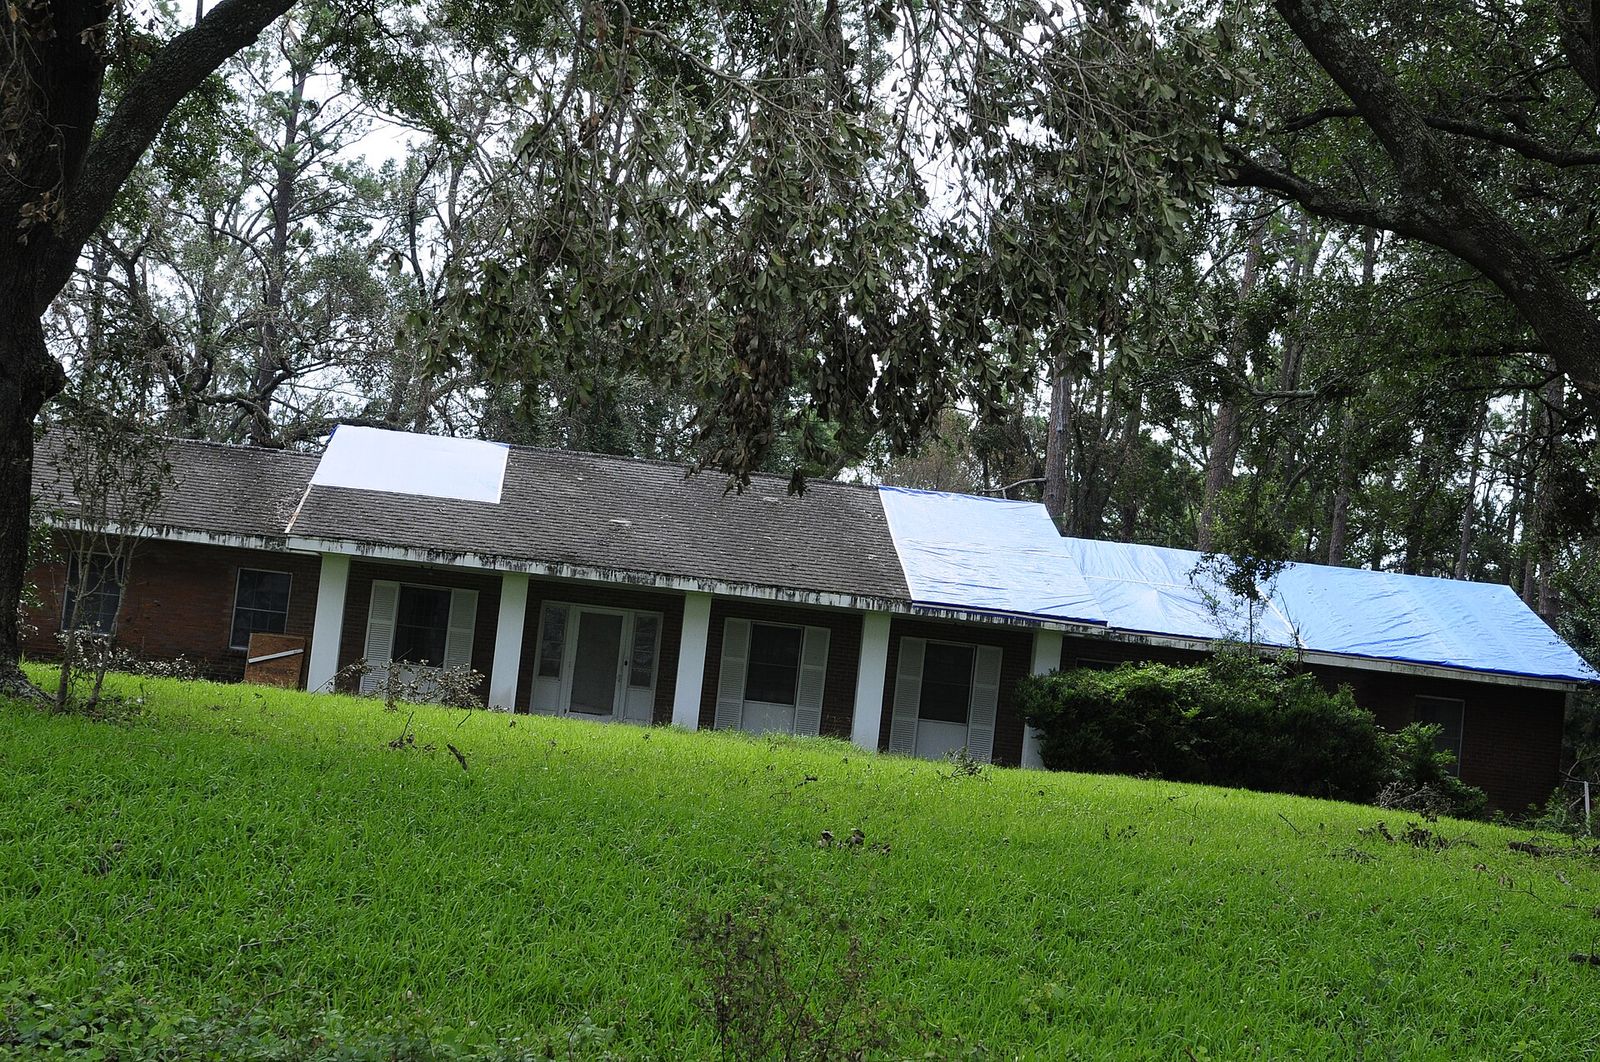
Residential and commercial property claims. Most of what comes through Chicagoland starts with wind or hail between April and September, and most of the rest starts with water in January and February.
Six steps in the order they happen. Nothing is signed until step two, and nothing is accepted without you.
Tell us what happened, when, and what the carrier has said so far. Keep every letter, estimate and photo they sent you.
We read the policy and whatever the carrier has written. If the claim looks fairly paid, we say so and that is the end of it. If we can help, we put our fee in writing and you sign before anything else happens.
We come to the property, photograph and measure, and write a line-item scope. Where the policy language matters, we quote it.
The scope and the documentation go to your insurance company. We handle the calls and the emails with their adjuster, and we answer disagreements with evidence.
Every offer comes to you with our read on it. You accept or decline. We never settle a claim without your say.
When the carrier pays, our fee comes out of that payment at the percentage in your contract. If there is no recovery, there is no fee.
A and D Adjusters is a new Illinois public adjusting firm based in Chicagoland. It is small on purpose: the person you talk to on the first call is the person who reads your policy, climbs the ladder and sits across from the carrier's adjuster. We take claims in Cook, DuPage, Lake, Will, Kane and McHenry counties and we come to the property, whether that is a bungalow in Berwyn, a two-flat in Cicero, a split-level in Naperville or a warehouse in Joliet.
"I started this firm because I kept seeing the same thing: a homeowner with a real loss, a policy they had never read, and a settlement letter they did not know how to answer. My job is to read the policy, document what actually happened and put the claim in front of the carrier in the language their adjuster uses. If the claim is already paid fairly, I will tell you that. If it is not, I will show you why."
Anahi, Public AdjusterPlaceholder: years in the trade, prior work, languages spoken and the office town go here once Anahi confirms them.
Placeholder. Reviews appear here once the first clients post on Google. Each one will show the client's first name, last initial, town, month and year, and a link to the review on Google. Nothing is quoted on this site that cannot be read on Google.
"Read all reviews on Google" links to the Google Business Profile once it is live.
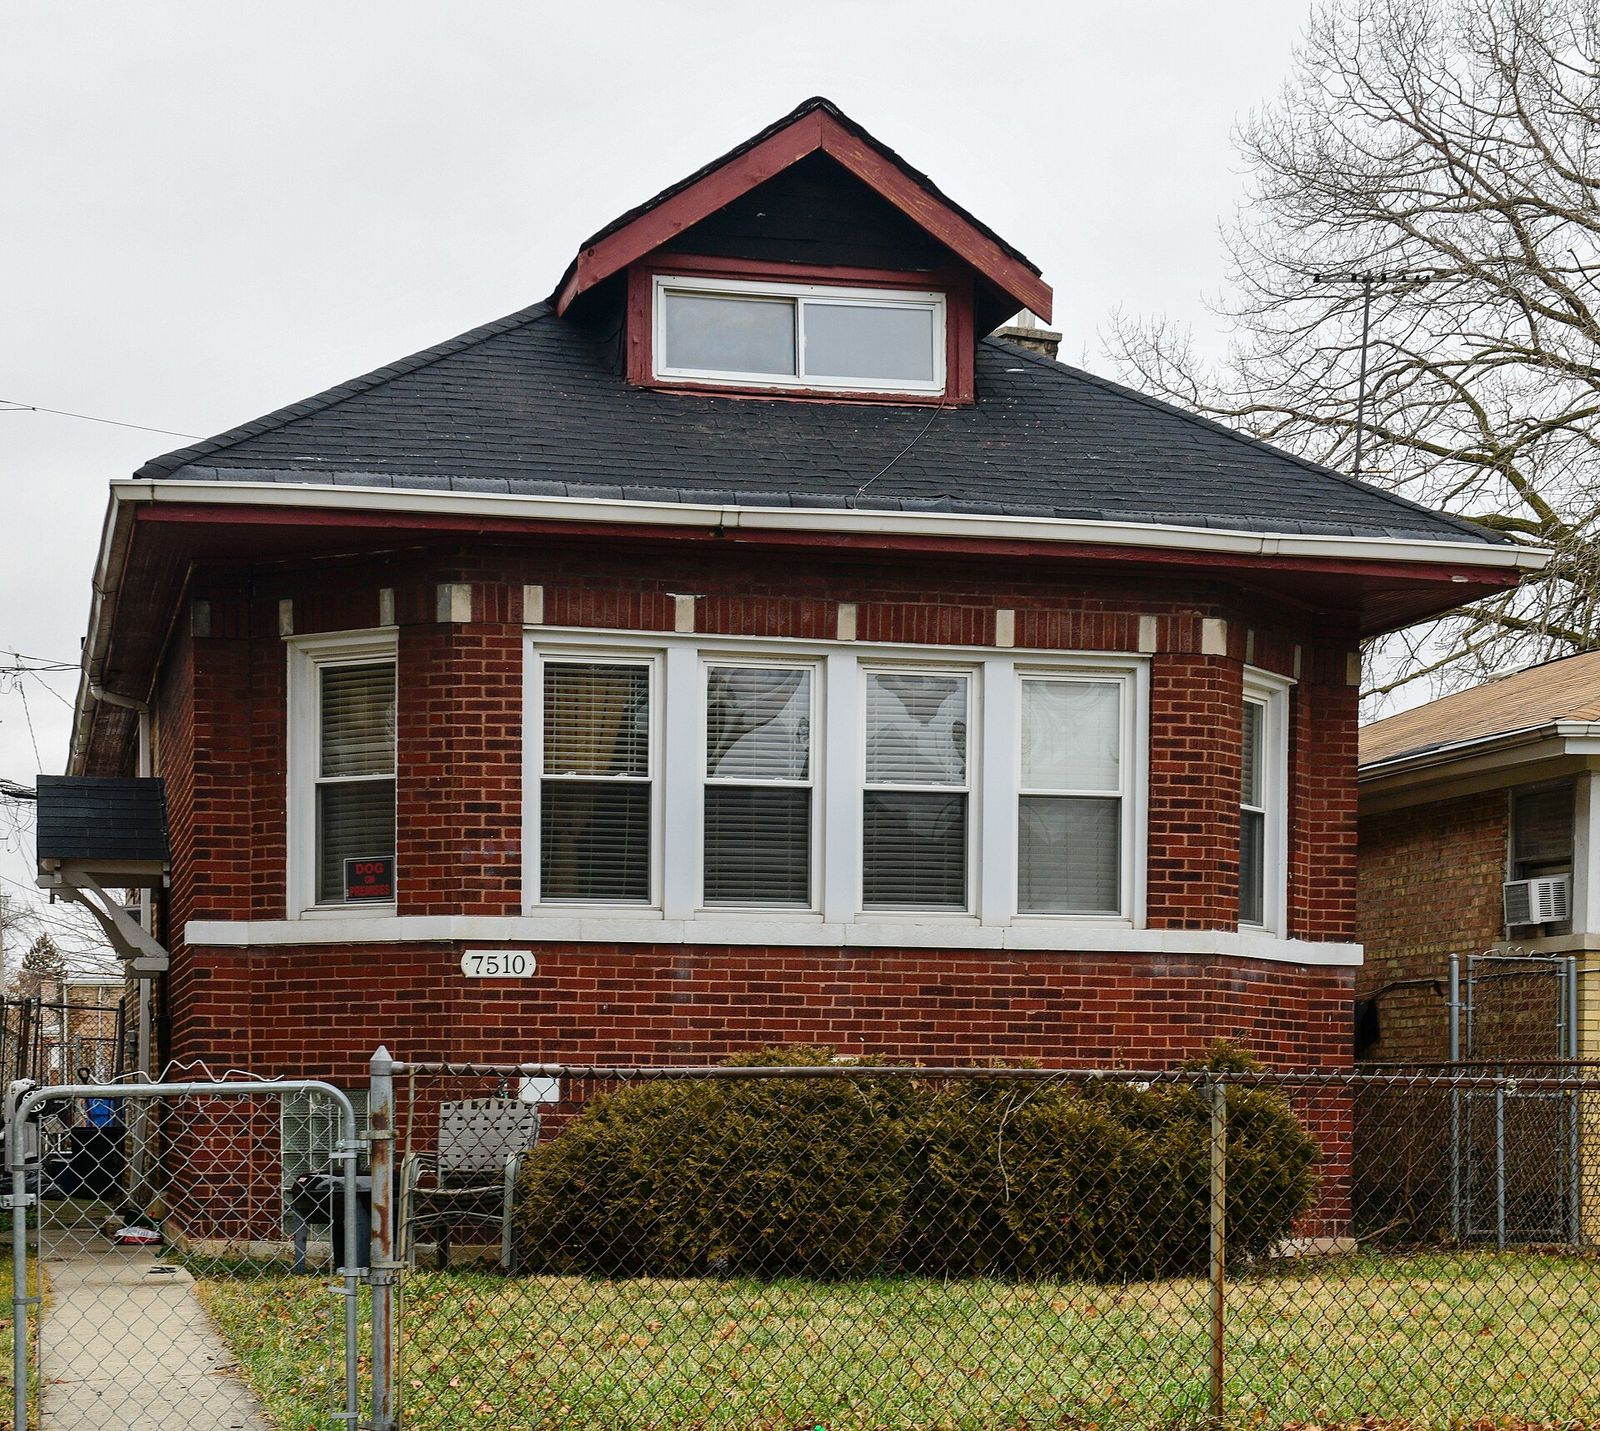
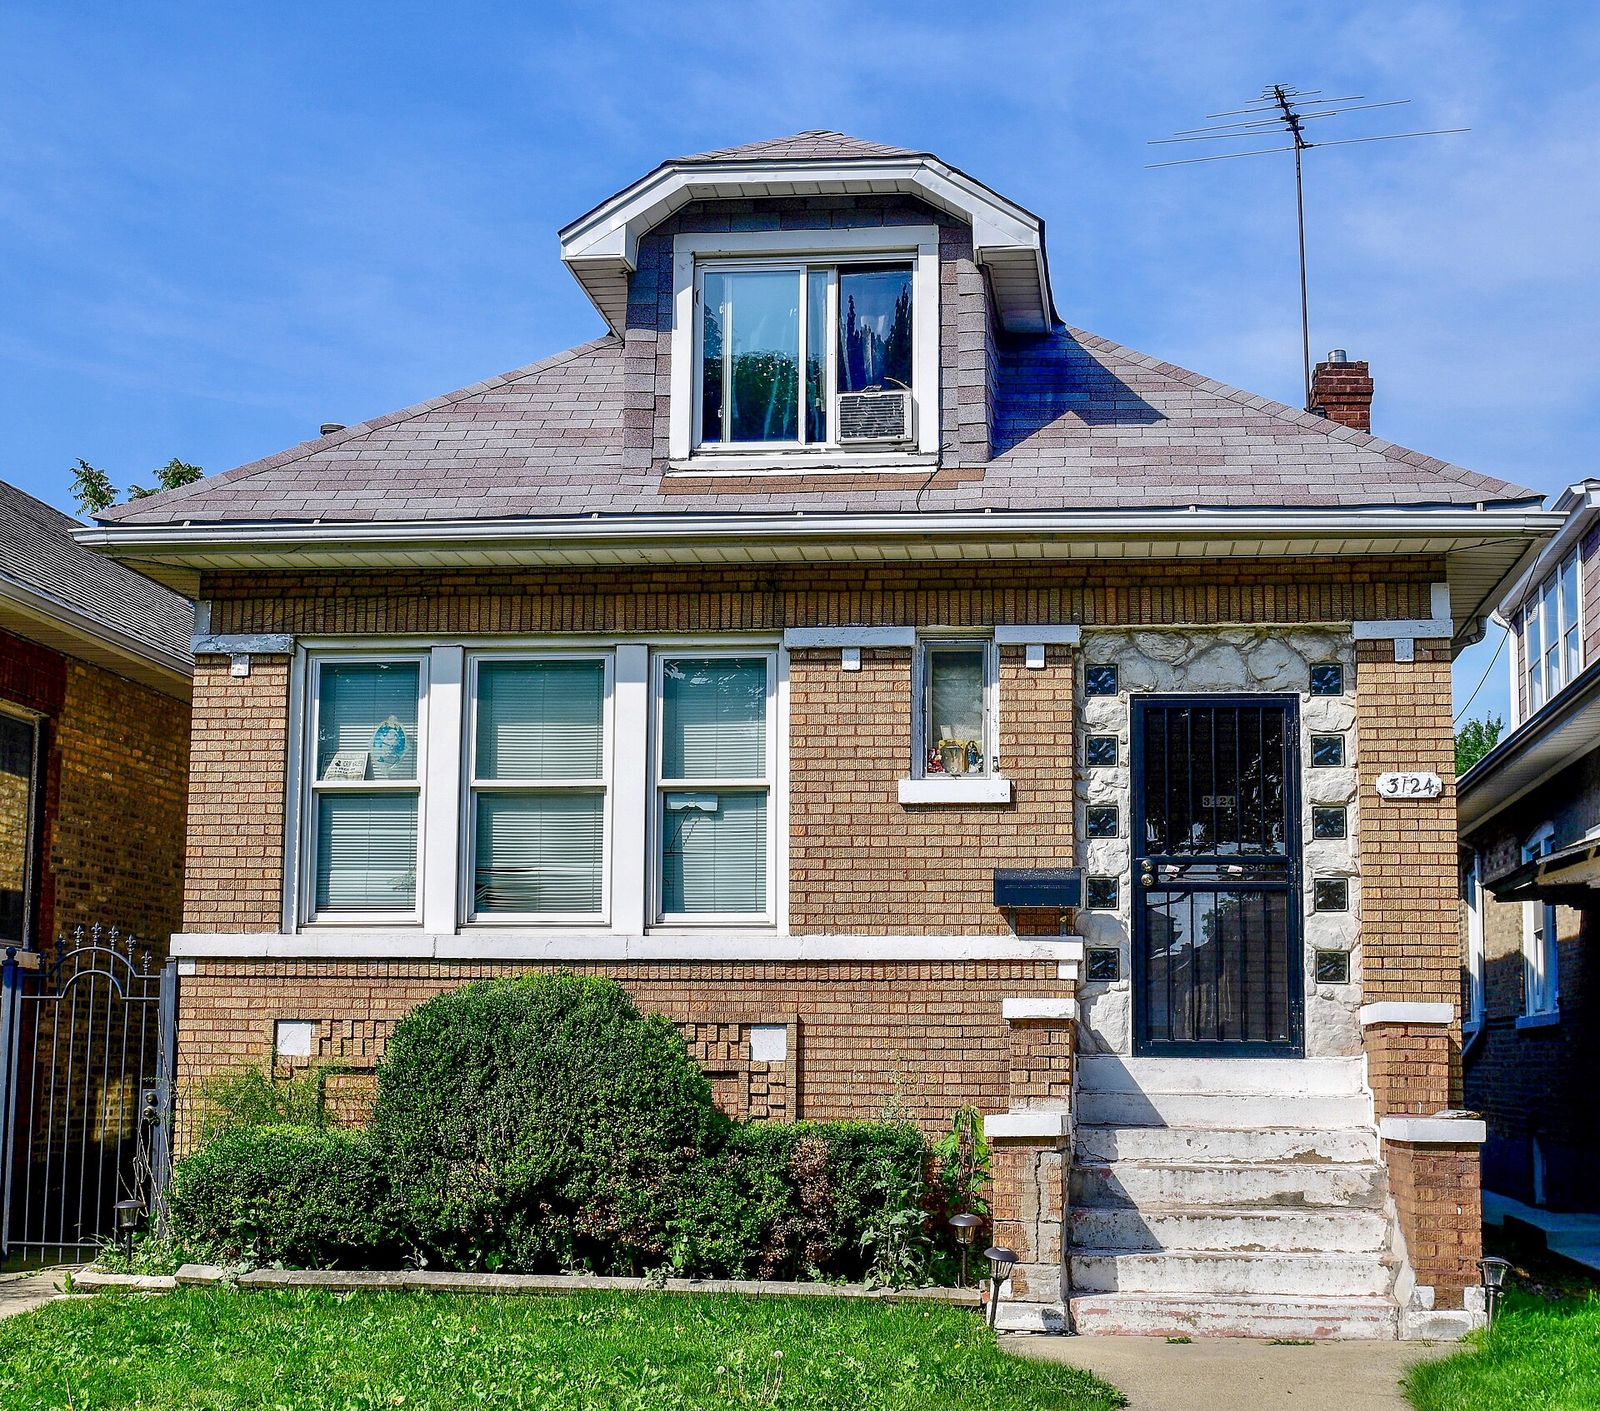
The buildings we work on: brick bungalows and two-flats inside the city, frame homes and townhouses in the suburbs, flat roofs on commercial buildings. Every photo here will be replaced with A and D's own job-site photos as claims are documented.
You may cancel a public adjuster contract within the period stated in the contract. Read every page before you sign, including ours.
You are never required to use a specific contractor for repairs. We do not recommend one, and no contractor pays us for referrals.
You can reach your insurance company directly at any time. Hiring a public adjuster does not take that away from you.
Tell us what the carrier said. We read the policy first and tell you honestly whether we can help. No cost and no obligation for the look.
(000) 000-0000
Placeholder until the business line is set up.
Fuentes.anahi@yahoo.com
A domain email address replaces this at launch.
Placeholder: office town or address to be confirmed. By appointment. We come to the property.